
Plano · Collin County
Sell a Fire Damaged House in Plano
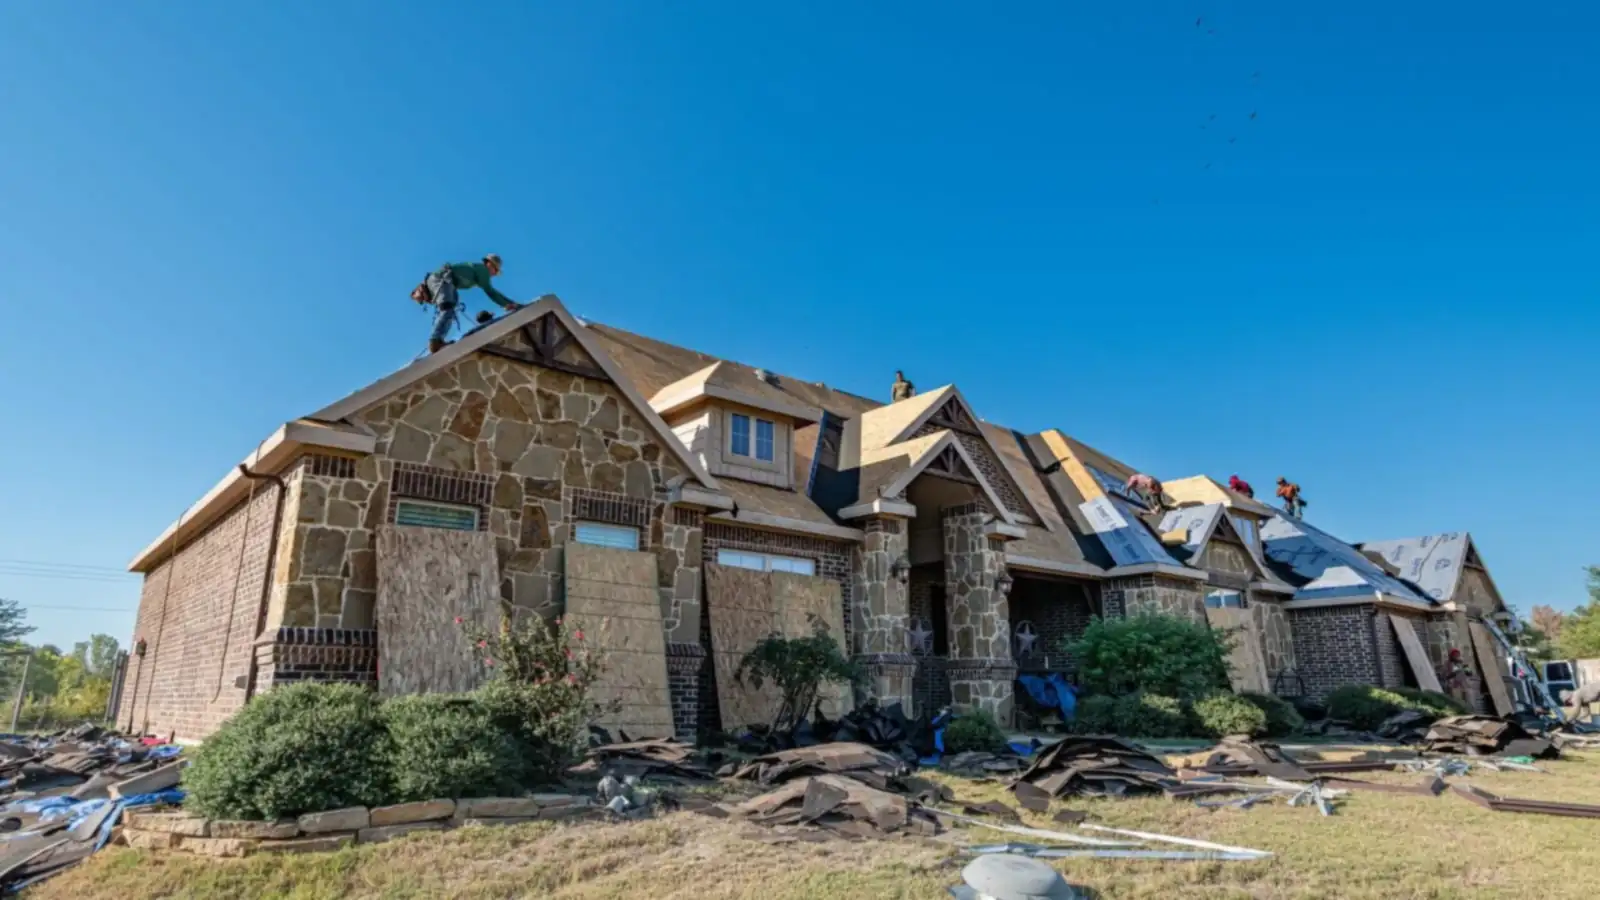
After a fire, the practical problem arrives before the financial one: you cannot live there, you may still owe on it, and almost nobody can buy it.
- Written offer within 24 hours
- No repairs, no cleaning, no showings
- We pay the closing costs
- You choose the closing date
-
 BBB accredited business
Look the accreditation up before you call us — it is a matter of record.
- Written offer within 24 hours A real number in writing, with the math we used to reach it. No fee, no obligation.
- Closing in 7 to 14 days On a clean title — or months out instead. You pick the date, not us.
- No commissions and no fees We pay the closing costs at a Texas title company. Nothing comes out of your side.
How it works
What are the steps to sell your Plano house for cash?
Tell us about the house
Address and condition is enough. We do not need photos, a cleanup, or a repair list — we buy as-is and we expect deferred maintenance.
Get a written offer in 24 hours
We price off recent Collin County sales and what the house actually needs. You get a real number in writing, with how we arrived at it.
Close on your date
Seven days if you need speed, or later if you need time to find your next place. Closing happens at a Texas title company and we cover the closing costs.
Cash offer vs agent vs iBuyer
Which of the three is actually right for your house?
If your Plano house is updated, empty and you can wait 60–90 days, listing with a good agent will usually net you more, and an iBuyer may too if the house fits its criteria. A cash sale wins when condition, a fixed date or certainty matter more than squeezing out the last few percent.
| Listing with an agent | iBuyer / instant offer | Sell My House Fast Plano | |
|---|---|---|---|
| Time to close | Typically 60–90+ days, plus time on market | Usually 14–60 days, inside the platform's window | 7–14 days on clean title, or later if you prefer |
| Agent commission | Commonly 5–6% of the price | None | None |
| Service fee | None separate from the commission | Yes — a percentage of the price, disclosed in the offer | None |
| Closing costs | Seller commonly pays 1–3% | Seller pays their share | We pay them |
| Repairs | Pre-list work, then buyer repair requests | None up front; deductions after their inspection | None, and no deduction after we look |
| Showings | Ongoing, plus open houses | None, but an inspection visit | One walkthrough |
| Financing contingency | Buyer's appraisal and loan can fall through | None — the platform pays cash | None — we pay cash |
| Condition accepted | Must satisfy the buyer's lender and appraiser | Newer, financeable houses within set criteria | Any condition — fire, hoarder, foundation, tenants |
| Who picks the closing date | Negotiated with the buyer | Chosen from the platform's window | You do |
Find out what your house is worth in cash
One visit, a written number within 24 hours, and no obligation at any point. If a cash sale is not your best option, we will tell you.
Get My Cash Offer Call (972) 928-0410Can you sell a fire damaged house in Plano?
Yes. Fire damaged houses in Plano generally cannot be sold to financed buyers, because lenders will not lend on an uninhabitable structure. A cash buyer purchases as-is with the damage in place — no cleanup, no contractors, and no requirement that you finish repairs an insurer paid for.
Last verified: August 16, 2026 · Plano, Collin County, Texas
Financed buyers are ruled out
No lender funds an uninhabitable house. That removes almost every retail buyer at a stroke and leaves cash purchasers, which is why fire-damaged houses sit unsold while the mortgage, taxes and vacancy insurance keep running.
You do not have to complete the repairs
Many owners take an insurance payout, start the work, and stall — a contractor walked, the money ran short, the scope grew. Selling with the job half finished is fine. We buy mid-repair as readily as untouched.
Open claims change the mechanics
Whether your claim is open or closed matters, because an open claim may still pay out and that has to be resolved at closing: who receives the remaining proceeds, and whether the mortgage company holds funds in escrow. Tell us early — it affects the paperwork, not whether we buy.
Smoke damage counts as damage
A house that never burned badly but absorbed heavy smoke can still be unsellable retail. Smoke gets into framing, ducts and insulation, and a buyer's inspector will find it. We price it and move on.
Insurance and disclosure
How the insurance claim, not the fire, sets the timetable
On a fire-damaged house the paperwork that decides your closing is the claim file. These are the four points that come up in every one of these purchases.
- Your lender may be holding the money
- A standard mortgage makes the lender a loss payee, so claim proceeds on a damaged house are commonly held and released against inspections of the repair work. Who holds what has to be resolved in the contract, not discovered at funding.
- Texas has a prompt-payment law for claims
- The Texas Insurance Code sets deadlines for an insurer to acknowledge, investigate and pay a claim once it has what it reasonably asked for. If your claim is stalled, those deadlines are worth reading before you accept that nothing can be done.
- Previous fire damage is a disclosure line
- The statutory seller's disclosure notice asks about previous fire damage specifically. It is not a reason a sale cannot happen; it is a reason the sale needs to be documented properly.
- Repairs need permits, and permits get inspected
- Structural, electrical and plumbing repair after a fire is permitted work. A permit left open or expired is the thing that surfaces when the next buyer's lender asks for the file, which is another reason a half-finished repair sells better to a cash buyer.
- An uninhabitable house is not lendable
- No lender funds a house that cannot be occupied, which removes essentially every financed buyer at a stroke and is why fire-damaged houses sit while the mortgage, taxes and vacancy premium keep running.
General information about Texas property, with the code references included so you can look each one up. It is not legal or tax advice — confirm your own position with an attorney or CPA before you sign anything.
Questions we get asked
Will you buy a house that burned badly?
Yes, including houses that are structurally compromised or close to a total loss. In the worst cases the value is mostly in the lot, and we will tell you when that is what we are pricing rather than pretending otherwise.
My insurance claim is still open. Can I sell?
Usually yes, but the claim has to be dealt with at closing — specifically who collects any remaining proceeds and whether your lender is holding funds in escrow. Raise it in the first conversation so it is handled in the contract rather than discovered a week before closing.
Do I need to clean up or secure the property first?
No. Leave it as it is, including debris and damaged contents. Do keep it boarded and insured if you can, because vacant fire-damaged property attracts further loss — but that is about protecting your position, not a condition of us buying.
What about smoke damage with no actual fire damage?
We buy those too. Heavy smoke penetrates framing, ductwork, insulation and drywall, and it does not wash out — a buyer's inspector will identify it and most retail buyers walk away once they smell it. Treat it as a real condition that gets priced into the offer rather than a cosmetic problem you could clean up before listing.